Direct Answer
“There’s no single right answer to whether you should keep the house or sell it in a North Carolina divorce. It depends on whether your kids need the stability of staying put more than you need the cash the house represents, and on whether you can actually afford to own it alone. Keeping the house can protect a child’s routine in the short term, but it can also leave you house-rich and cash-poor for years. A North Carolina court weighs a custodial parent’s need for the home as one factor among several — never a guarantee — so the real decision usually comes down to your income, your mortgage, and what you’re willing to trade to keep the walls the same.”
— Connor Wallace Green, Junior Associate Attorney, Cape Fear Family Law

Should I keep the house or sell it in a North Carolina divorce?
I get asked some version of this question in almost every separation consultation, and it’s usually not really about the house. It’s about whether staying put is right for the kids, and whether that answer matches what you can actually afford. Sometimes it does. Often it doesn’t, and that gap is where most bad decisions in a divorce get made.
This page is written for three groups: parents in a custody dispute deciding whether the house is worth fighting for, separating individuals sorting out property before anything is filed, and families pursuing adoption who are managing a household’s financial picture at the same time a home study is reviewing it. If you’re weighing this out in Charlotte, Matthews, or anywhere else in Mecklenburg County, here’s how the two arguments actually work — and where they conflict.
Imagine a recently separated couple, let’s call them Mike and Sally. Mike and Sally have a son, Jimmy, who is five-years old. Jimmy has been in the home his entire life and just started kindergarten in the area. Sally is adamant about keeping the home and, at first, she is willing to give up anything for it. Sally has a retirement account that she opened up during the marriage with $75,000 in it. Sally went to check and the house was listed at $200,000 on Zillow. Sally thought trading her retirement account funds for the home was a no-brainer.
Then, Sally scheduled a consultation with a family law attorney to discuss her plan. The attorney asked her whether the house had a mortgage attached to it. Sally said that the house has a mortgage of $100,000. Her attorney asked her who is currently paying for the mortgage, which is roughly $2400 per month. She informed her attorney that she and Mike have been splitting the mortgage payments. Her attorney asked her if she was able to comfortably pay the mortgage on her own, which she said she thinks so. The attorney asks her the same questions about HOA fees, utilities, and other common expenses that come with owning a home. Now, Sally was less sure what she wanted to do with the house.
Her attorney advised her that although the value of the home would likely increase in value as long as the housing market continues to grow, the expenses of owning a home and the lack of liquidity can be a downside compared to a retirement account, which grows passively and does not require all of these additional expenses.
Sally ended up deciding that being able to keep the home and provide that stability for Jimmy at a crucial time in his life was something to prioritize and she decided to keep the home. Ultimately, she was comfortable trading the financial benefits of keeping the retirement account for the stability and comfort of keeping the home.
The short-term case: what stability is actually worth to a child
The short-term argument is simple: kids do better with fewer changes happening at once. A separation already disrupts routine, school pickup, and friend groups. Keeping the same bedroom, bus stop, and block absorbs some of that shock. North Carolina law recognizes this directly — a court dividing property weighs the need of a parent with custody to occupy or own the marital residence as one factor in the analysis, because judges see the same pattern you’re worried about: kids handle a hard year better when at least one part of their life doesn’t move.
Here’s what gets skipped in a lot of what’s written about this: that factor supports an argument. It does not create a right. Nothing promises a custodial parent the house, and a court keeps full authority to order it sold if that’s the equitable outcome once everything else is weighed. A single factor, backed by real evidence — school records, a child’s therapist, a clear account of what a move would cost — can support an unequal division in your favor. Asserted without anything behind it, that same factor rarely moves much at all.
That distinction matters more if you’re already in a high-conflict custody case. If you’re dealing with a co-parent who turns every logistical decision into a fight — and if any of what you’ve seen under the “co-parenting with a narcissist” label online sounds familiar — the value of stability isn’t abstract. It’s one less thing your child has to adjust to while everything else about their family is changing. That’s a legitimate reason to want the house. It’s just not the only side of the ledger.
The long-term case: is the house a good asset to take?
Here’s the argument nobody wants to make out loud in the middle of a separation: the house might not be the asset you actually want.
In a large share of North Carolina marital estates, the house and the retirement accounts are the two assets that matter most. Taking the house usually means giving up a larger share of the retirement to balance the scales. That trade deserves an honest look, not an assumption that keeping the house is automatically the win.
| What You’re Comparing | The House | The Retirement Account |
|---|---|---|
| Liquidity | Illiquid — turning equity into cash means selling, refinancing, or borrowing | Liquid at a distance — accessible on a timeline, without a sale |
| Ongoing cost | Mortgage, insurance, property tax, repairs, and a roof that eventually needs replacing | No maintenance cost; management fees are typically minimal |
| Diversification | A single asset, in a single location, exposed to your local market | Usually spread across many holdings, less exposed to one local market |
| Growth pattern | Appreciation is uneven and depends on the local market and upkeep | Growth compounds over time without your active involvement |
| Day-to-day demand on you | High — someone has to maintain it, insure it, and pay for it every month | Low — it sits and grows without your attention |
Taking the retirement share and renting for a few years is a genuinely reasonable choice for some families — not a consolation prize. It buys you time to see where you’ll actually want to live once the dust settles, without the maintenance calls and the property tax bill landing on you alone.
What does it cost to buy out my spouse’s share?
There’s no calculator for this any more than there’s one for alimony — the number depends on your specific facts, not a formula you can plug into online. But the concept is straightforward. A buyout is generally built from the home’s equity — value minus what’s owed on the mortgage — with each spouse’s share based on how that equity is classified.
For the piece that counts as marital property, North Carolina values it as of the date of separation. Anything that happens to the home’s value after separation and before the case is resolved — appreciation or depreciation — falls into a separate category called divisible property, and it’s valued as of the date the case is actually distributed, not the date you separated. That distinction matters more than most people expect: if the market moves after you split up, that later change is classified differently than the value that existed on day one.
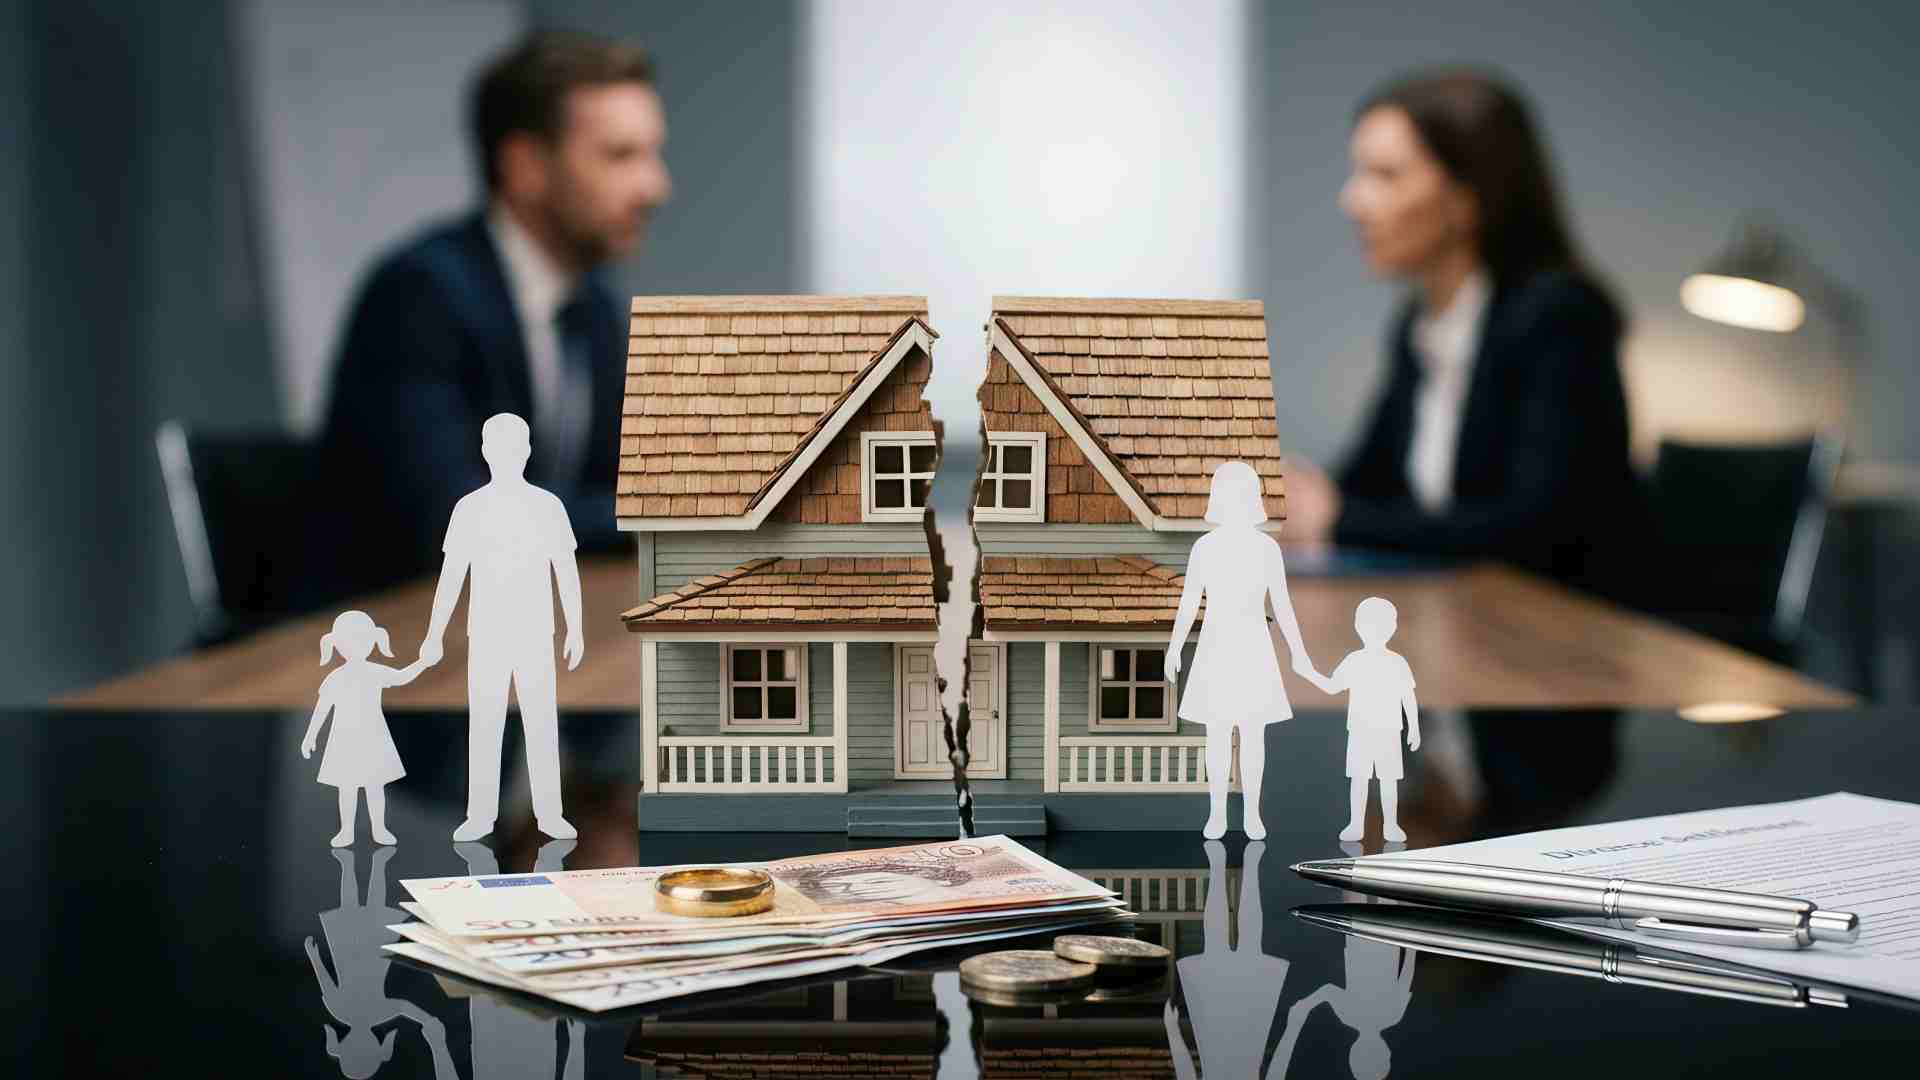
When a house can’t practically be split down the middle — and most houses can’t — North Carolina allows the court to order a distributive award instead: a payment, in a lump sum or over time, that makes the other spouse whole for their share. That award can be secured by a lien against the property itself, which is one reason a buyout should be documented properly rather than handled with a handshake.
If you’ve been paying the mortgage alone since you separated, that doesn’t disappear into the wash. North Carolina courts can enter interim orders crediting a spouse for post-separation payments toward marital debt, and a court weighs whether either spouse acted to maintain — or, on the other end, to waste or devalue — the property during that window. Bring your statements. This is exactly the kind of thing a documented record wins and a guess loses.
Can I refinance on one income?
This is a mortgage question, not a legal one, and I’ll tell you honestly when that line gets crossed. What I can tell you as your attorney: a divorce decree or separation agreement that says you’re keeping the house does not, by itself, get your spouse’s name off the mortgage. A deed transfer changes who owns the property. It does not touch the loan. Your spouse can sign a quitclaim deed and still be legally on the hook for that mortgage unless the loan itself is refinanced into your name alone — and a lender, not a judge, decides whether you qualify to do that.
Whether you can actually refinance on one income, what rate you’d get, and how much cash you’d need to bring to the table are questions for a mortgage professional, not for this page. Talk to a lender early — before you agree to keep the house, not after — so you know whether the plan is realistic before you’ve given up something else to get there.
What am I giving up to keep the house?
This is the section I’d want a lawyer to be straight with me about, so I’m going to be straight with you.
Keeping the house usually means giving up a larger share of the retirement, investments, or cash that would otherwise balance the division. That money is tied up in the walls around you instead of in an account you could draw on for a lawyer, a deposit, or an emergency. And it commits you to a mortgage, taxes, insurance, and maintenance on one income, at the exact moment that income is under the most pressure it’s faced in years.
And here’s the sentence I want you to actually sit with: some people should not keep the house. A parent who is stretched to the edge by a mortgage is a less available parent — more stressed, more tired, less patient — and courts notice that, and so do kids. The house that was supposed to protect your child’s stability can end up costing you the thing stability was supposed to protect in the first place, if it leaves you too strained to show up the way you want to.
Imagine a different couple, Bob and Susan. Bob and Susan have a ten-year old daughter, Cindy. Bob and Susan disagree about what to do with their house. Bob wants to sell the home and split the net proceeds. Susan wants to keep the house and reside there with Cindy as the primary caretaker. Bob tells Susan he is willing to allow her to remain in the home if Susan buys out his marital interest in the home, which they value at $30,000. Susan has $3,000 in her bank account and agrees to pay Bob $3,000 initially with subsequent monthly payments of $2,000 per month until the remainder of the $30,000 is paid off. Bob agrees and the parties execute a separation agreement to that effect. In the agreement Susan’s payments are attached to a lien on the marital residence. The parties also agree that Susan can be the primary caretaker of Cindy although they never put anything in writing to that effect.
Susan is now responsible for paying the mortgage payments on her own, which amount to $2,500, as well as utilities, HOA fees, and other payments. In total, Susan pays an average of $3,200 per month on all of those fees. In addition to that she is not contractually obligated to pay Bob $2,000 per month. Susan has to get a second job to keep up with all of these payments and that makes it harder for her to spend time with Cindy. Susan is exhausted from working two jobs and needs Bob to watch Cindy while she is working. Bob documents this changed custody arrangement and eventually files a child custody action with the courts. The Court sees that Susan is working hard but that she is no longer able to be the primary caretaker. Ultimately, the Court awards joint physical custody to both parents and Susan loses out on her ability to be the primary caretaker.
What if I keep it and cannot afford it in two years?
Say the plan looks fine on paper today and falls apart in eighteen months — the math was closer than it looked, a job changed, or the refinance never fully happened and your ex is still legally tied to that mortgage. This isn’t rare. Plan for it before you agree to keep the house, not after you’re already underwater.
Build in an honest checkpoint — twelve to eighteen months out — where you actually look at whether the plan is working, instead of assuming it will. If a refinance was supposed to happen and didn’t, solve that immediately; your ex-spouse’s ongoing legal exposure on that loan is real, and it can come back around on both of you. If you do end up needing to sell later, having documented the reasoning and the numbers from the start puts you in a far stronger position than reconstructing it under pressure.
Is there a middle option between keeping and selling?
Yes, and this is the part most people never get told exists: keeping the house and selling the house are not the only two doors in the room.
North Carolina law lets separating spouses agree to their own property arrangement by written agreement, and a well-drafted one can build in a middle path instead of forcing an immediate choice.
| Option | How It Works | What It Requires |
|---|---|---|
| Deferred sale with exclusive possession | One spouse stays in the home for a defined period — often tied to the kids’ ages — while both names may remain on the deed until the sale | A written agreement or consent order spelling out who pays the mortgage and upkeep, and how proceeds split when it sells |
| Buyout structured over time | Instead of one lump payment, the buying spouse pays the other spouse’s share on a set schedule | A distributive award, which can be secured by a lien on the property so the payment is actually enforceable |
| Offset against another asset | One spouse keeps the house; the other takes a larger share of retirement, investments, or cash to balance it | An accurate valuation of both the house and the offsetting asset — this is where an appraisal earns its cost |
| Sale at a trigger event | The house isn’t sold now — it’s sold when something specific happens: a child’s graduation, emancipation, or a parent’s remarriage | Clear, specific drafting of what the trigger is, who covers costs until then, and how any dispute about timing gets resolved |
None of these happen by default. Each one has to be negotiated and drafted correctly, or it turns into the exact argument you were trying to avoid three years from now. [INTERNAL LINK: separation agreements in North Carolina] walks through how these get built into an enforceable document rather than a verbal understanding that falls apart the first time someone misses a mortgage payment.
Keep-or-sell FAQ
Do I automatically get to keep the house if I have custody?
No. A court can consider a custodial parent’s need for the home as one factor in dividing property, but it isn’t a right or a presumption — the house can still be ordered sold if that’s the equitable outcome once everything else is weighed.
What happens to the house if my spouse and I can’t agree?
If you can’t reach an agreement, a judge decides — including whether the house is awarded to one spouse, sold with proceeds divided, or handled through a distributive award that pays the other spouse their share over time.
Does it matter whose name is on the deed or the mortgage?
It matters, but it isn’t the whole story. A home purchased during the marriage is generally treated as marital property regardless of whose name is on the deed, and being on the mortgage note is a separate legal question from owning the title.
What if I owned the house before we got married?
Property owned before the marriage generally starts out as separate property, but marital funds used to pay the mortgage or improve the home during the marriage can create a marital interest in it — a fact pattern worth reviewing with an attorney rather than assuming either way.
Does infidelity affect who keeps the house?
Generally, no. North Carolina’s property division statute does not list marital misconduct or infidelity as a factor the way alimony law does. The one place conduct can matter is if marital money was spent in a way that wasted or converted marital assets — that’s assessed separately from any misconduct itself.
Can we agree to sell the house later instead of choosing now?
Yes. North Carolina lets separating spouses put a deferred sale, a trigger-event sale, or a structured buyout into a written agreement, as long as it’s drafted clearly enough to actually hold up when the trigger arrives.
Do I need an appraisal?
If you’re buying out a spouse’s share or offsetting the house against another asset, an accurate valuation is the foundation everything else is built on — a number one of you guessed at is a number the other side can challenge.
What if my spouse won’t leave the house?
This depends heavily on your specific facts, including whether there’s a safety concern, and it’s not a question to work through alone — talk to an attorney about the options available in your situation before deciding what to do next.
Two arguments, two timelines, one decision.
Download: Why the House Should Stay With the Children — build the short-term record and the long-term math in one document.